Sources of Finance (AQA A Level Business): Exam Questions

Exam code: 7132

Syllabus Edition

First teaching 2026

First exams 2028

2 hours15 questions
1
6 marks

Source B: Mishcon de Reya LLP

Mishcon de Reya LLP is a law firm. It advises businesses and wealthy individuals on disputes, property, corporate deals and private matters, and it is led by managing partner James Libson. It has offices in London, Cambridge and Oxford, and overseas in Hong Kong, Singapore and the United Arab Emirates. About 1 250 people work there, including more than 650 lawyers.

It is not a company. It is a limited liability partnership, which means it is owned by its members, the partners, rather than by shareholders. Members put capital into the firm when they join and take a share of the profit rather than a salary. Nobody outside the partnership owns any part of it.

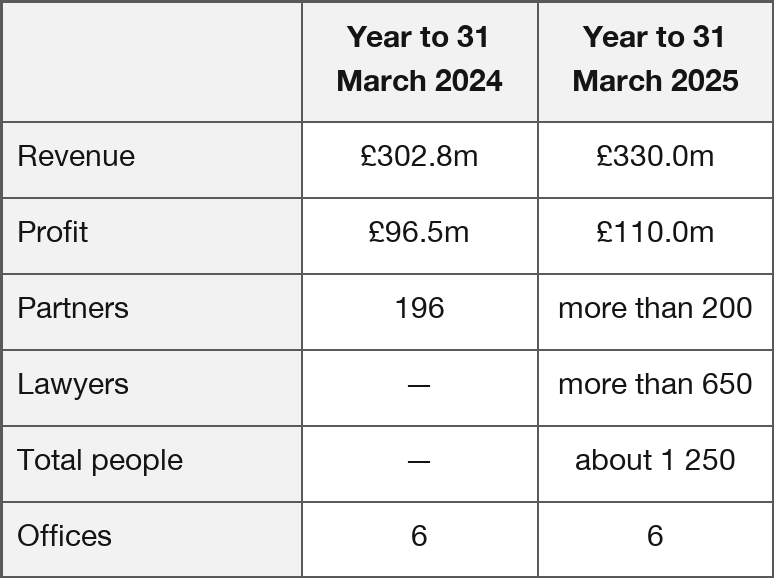
The year to 31 March 2025 was the firm's best. Revenue rose 9% to £330 million and profit rose 14% to £110 million, the first time it has passed £100 million. The firm says it has tripled in size over the past decade. Its work during the year included advising Wayve on what it describes as Europe's largest artificial intelligence investment and defending O2 in a collusion claim.

Growing has meant admitting people. Sixteen new partners joined during the year and a further 27 people were promoted to partner from inside the firm, alongside 13 promotions to legal director. There are now more than 200 partners. As in any partnership, some members retire or leave each year, so membership grows by less than the number admitted.

That is the tension the firm is sitting with. In a partnership the profit is divided between the members, so every partner admitted is another share of the same pool. The firm now has to decide where its next stage of growth should come from: more partners in the United Kingdom, where it already has three offices and knows the market, or a bigger presence in Hong Kong, Singapore and the United Arab Emirates, where the offices exist but are small. Appendix F sets out the two options.

Source: information sourced from Mishcon de Reya LLP, results for 2024/25

Appendix D: Mishcon de Reya LLP selected results

Selected results for years to 31 March 2024/2025: revenue £302.8m/£330.0m; profit £96.5m/£110.0m; partners 196/over 200; lawyers —/over 650; total people —/about 1,250; offices 6/6.

Source: Mishcon de Reya LLP; 2024 partner number from analyst estimates
Mishcon de Reya LLP is owned by its members, who put capital into the firm when they join.

Analyse one way in which Mishcon de Reya LLP could raise the money to open a new office.

2
6 marks

Source A: Ridgeway Signs

Tomasz Nowak trades as Ridgeway Signs. He is a sole trader, which means the business is not separate from him in law: he owns everything it owns and he is personally responsible for everything it owes. He has no employees and works from a rented unit on a small industrial estate, with a van.

He designs, prints and fits signs for local businesses: shop fascias, vehicle graphics, banners, menu boards and exhibition displays. Almost all of his customers are other businesses within about twenty miles. Every job is quoted separately, and he wins roughly one quote in three.

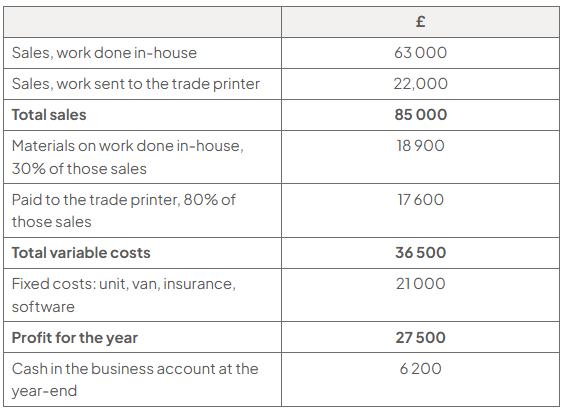
Last year Ridgeway Signs took £85 000. Materials cost about 30p in every pound of work Tomasz does himself, so he keeps about 70p. Rent on the unit, the van, insurance and design software cost £21 000 a year whatever he sells.

The business has a shape to it. Appendix B shows sales month by month. October and November are his best months, because retailers refit before Christmas, and January and February are his worst.

There is one piece of work he cannot do. Large-format printing, such as vehicle wraps and big banners, needs a machine he does not own, so he sends those jobs to a trade printer in another town. Last year that work was worth £22 000 of his sales, but the trade printer takes most of it: Tomasz keeps only about 20p in the pound. He also turns away large jobs when the trade printer is busy.

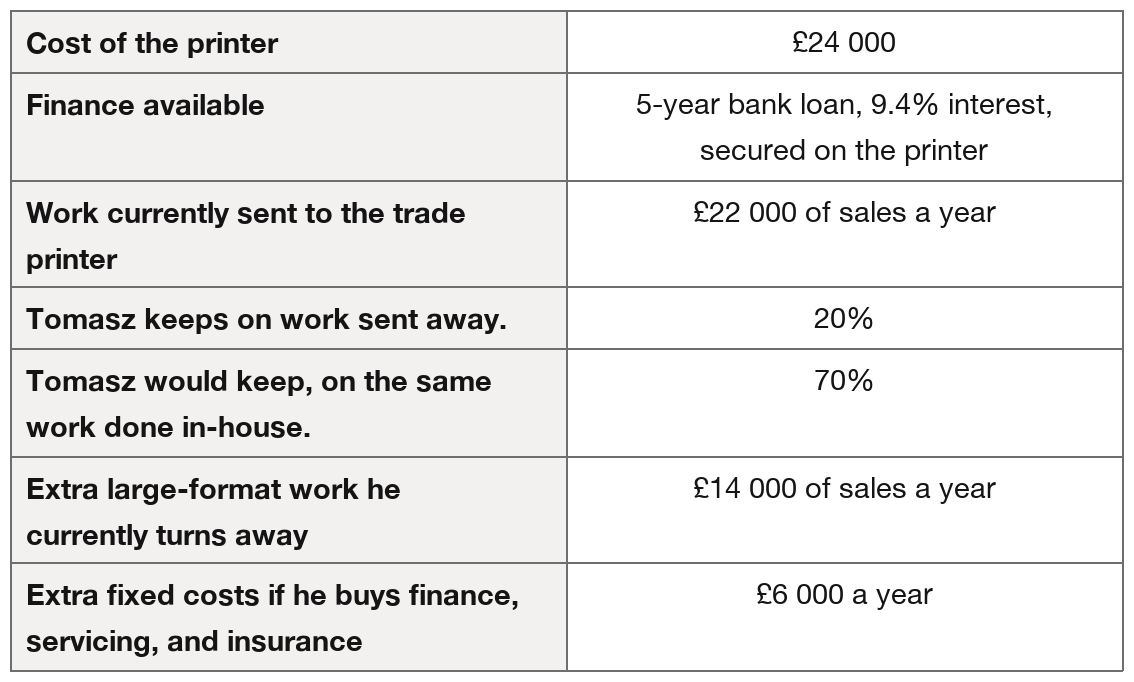
A wide-format printer costs £24 000. Tomasz has £6 200 in the business account. Appendix C sets out what his accountant thinks would happen if he bought one.

Appendix A: Ridgeway Signs, summary of last year

Table of Ridgeway Signs’ finances in pounds: in-house sales £63,000, trade-printer sales £22,000, total sales £85,000; variable costs £36,500, fixed costs £21,000, profit £27,500 and year-end cash £6,200.

Source: Analyst

Appendix C: Data on buying a wide-format printer

Table of data on buying a wide-format printer: cost £24,000; five-year bank loan at 9.4% interest secured on the printer; £22,000 of outsourced sales, 20% retained, £14,000 extra sales available, and £6,000 annual extra fixed costs.

Source: Analyst

Tomasz Nowak trades as a sole trader and has £6 200 in the business account.

Analyse one way in which being a sole trader might affect how Tomasz raises the £24 000 he needs for a printer.

3
6 marks

Source B: Fairhurst Linen Ltd

Fairhurst Linen Ltd is a commercial laundry on an industrial estate outside Leeds. It is a private limited company owned by Dev Anand and his sister Rani Anand, and it employs 24 people. It washes, presses and delivers bed linen, towels and table linen for hotels and restaurants across Yorkshire, and it charges by the kilogram.

Last year it processed 3.1 million kilograms at an average of 60p a kilogram, which brought in £1 860 000. Detergent, water, energy and packaging cost 20p for every kilogram put through the machines. Everything else is fixed: wages of £624 000 and premises, machines, maintenance and insurance of £456 000, which together come to £1 080 000 a year and are paid whether the machines run or not. Profit for the year was £160 000.

The machines are not full. They could handle 4.2 million kilograms a year, and last year they did 3.1 million. A new tunnel washer costing £320 000 would raise that ceiling further, and Dev Anand has been talking to the bank about it.

The Anands have set themselves an objective: a profit margin of 15% within three years.

Two things complicate the plan. The first is a contract. A hotel group has offered Fairhurst Linen Ltd 900 000 kilograms a year, which would nearly fill the machines, but only at 44p a kilogram, against the 60p its other customers pay. The second is that Fairhurst Linen Ltd pays its detergent supplier, a small chemicals firm in Rotherham, after 90 days, while its own hotel customers pay it after 45.

Fairhurst Linen Ltd needs £320 000 for a new tunnel washer and Dev Anand has been talking to the bank about a loan.

Analyse one way in which borrowing the money rather than saving up for it might affect Fairhurst Linen Ltd's costs.

4
6 marks

Source B: Halvergate Storage Ltd

Halvergate Storage Ltd rents storage units by the month. It has three sites in East Anglia, at Norwich, King's Lynn and Lowestoft, with 1 200 units between them. It is a private limited company owned by two brothers, Tom and Michael Ferris, and it employs nine people.

Its customers are households between moves, people who have downsized, and small businesses storing inventory. A unit costs an average of £100 a month. Once a unit is let it costs Halvergate Storage Ltd about £12 a month in electricity, cleaning and administration. Everything else is fixed: staff of £290 000 a year and rates, insurance and maintenance of £186 000, which are paid on the whole building whether the units inside it are full or empty.

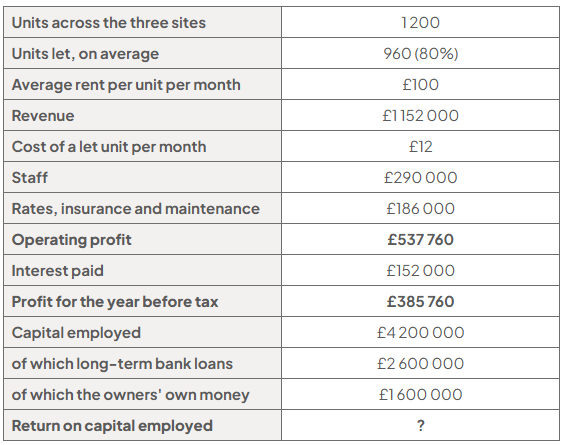
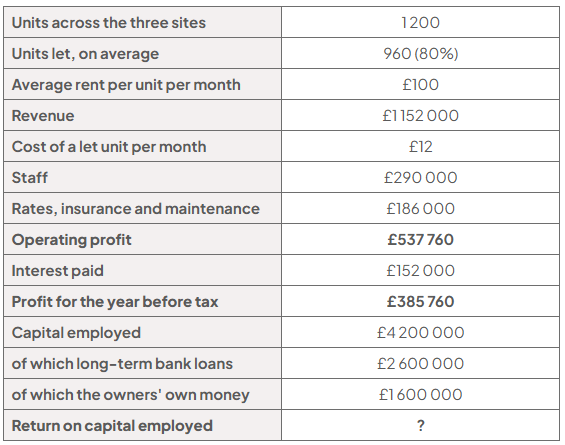
Last year 80% of the units were let, which is 960 of the 1 200, and revenue was £1 152 000. Operating profit was £537 760. After £152 000 of interest, profit for the year before tax was £385 760.

The interest is there because the sites were built with borrowed money. The three sites together represent capital employed of £4.2 million, of which £2.6 million is long-term bank loans and £1.6 million is the brothers' own money.

Tom and Michael Ferris have set the company an objective: a return on capital employed of 15% within three years. They are also looking at a fourth site, at Bury St Edmunds, which would cost £1.6 million.

Appendix D: Halvergate Storage Ltd, summary of last year

Appendix D summary table: 1,200 units, 960 let at 80%, £100 average monthly rent and £12 variable cost; fixed costs are £290,000 staff and £186,000 rates, with £152,000 interest on £2.6m loans.

Source: Analyst

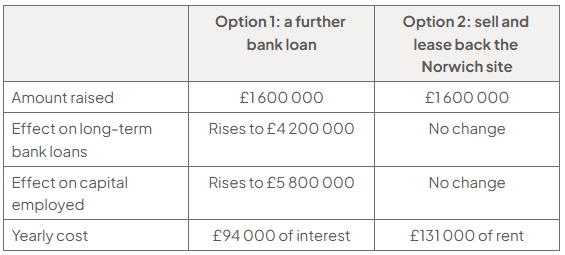
Appendix F: Data for two ways of paying for a fourth site

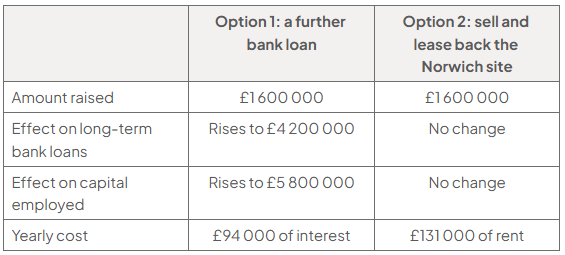
Table comparing £1,600,000 funding options: a further loan raises long-term loans to £4,200,000, capital employed to £5,800,000 and costs £94,000 interest yearly; leaseback leaves loans and capital unchanged and costs £131,000 rent.

Source: Analyst

Halvergate Storage Ltd's three sites were built using £2 600 000 of long-term bank loans alongside £1 600 000 of the Ferris brothers' own money.

Analyse one way in which having borrowed more than half the capital might affect the risk Halvergate Storage Ltd carries if fewer units are let.

5
6 marks

Source B: Kettleby Plant Hire Ltd

Kettleby Plant Hire Ltd hires excavators, dumpers and telehandlers to builders across the East Midlands. It is a private limited company owned by Sean Kettleby and it employs 22 people, including four fitters who service the machines and two drivers who deliver them.

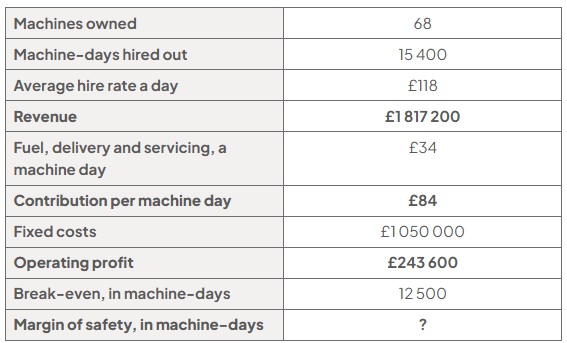
It owns 68 machines. Last year they were out on hire for 15 400 machine-days in total, at an average of £118 a day, which is revenue of £1 817 200. Fuel, delivery and servicing cost £34 for every day a machine is out. Everything else costs £1 050 000 a year and is paid whether the machines are out or standing in the yard.

Its customers are not alike. National housebuilders take more than half the revenue and are given sixty days to pay, which in practice becomes seventy-one. Small builders and sole traders are given seven days, or asked for a card when they collect. Sean Kettleby set it up that way and is candid about why: the housebuilders would go elsewhere if he pushed them, and the sole traders would not.

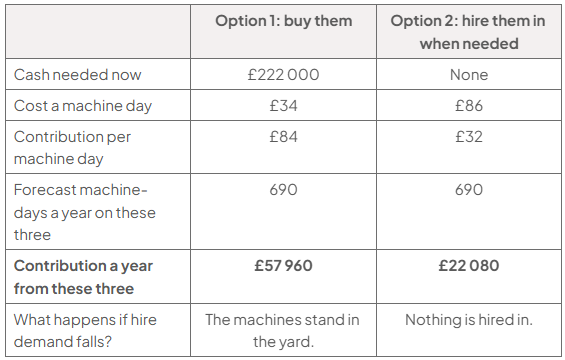
The machines are wearing out. Three excavators need replacing this year at £74 000 each. Sean Kettleby can buy them, which is what he has always done, or he can hire them in from a larger national firm when a customer needs one and hand the margin over. The bank has offered him a five-year loan for the £222 000, and he has enough in the company to pay cash if he chooses to.

Appendix D: Kettleby Plant Hire Ltd, summary of last year

Table of Kettleby Plant Hire Ltd’s data: 68 machines, 15,400 machine-days, £118 average daily rate, £1,817,200 revenue, £34 variable cost per day, £84 contribution, £1,050,000 fixed costs, £243,600 profit, 12,500 break-even days and unknown margin of safety.

Source: Analyst

Appendix F: Data for the three replacement excavators

Comparison table: buying needs £222,000 cash, costs £34 per machine-day and yields £57,960 annual contribution; hiring needs no cash, costs £86 per day and yields £22,080. Both forecast 690 days.

Source: Analyst

Three of Kettleby Plant Hire Ltd's excavators need replacing this year at £74,000 each.

Analyse one way in which paying for them out of Kettleby Plant Hire Ltd's own cash rather than borrowing might affect the cash it has available for day-to-day running.

6
6 marks

Source B: Paper Lane Ltd

Paper Lane Ltd sells stationery, cards and gifts from two small shops in market towns about 15 miles apart. Nina Okafor and Rhys Pritchard opened the first shop nine years ago and set the business up as a private limited company, with the two of them as the only directors and shareholders. They now employ nine other people, most of them part time.

The shops sell notebooks, pens, wrapping paper, cards and small gifts. Customers come in to browse, and a large share of what they buy was not on a list when they walked through the door. Nina and Rhys buy most of their inventory from small makers and from two wholesalers, and they order the Christmas range in August to get an 8% early order discount.

The business makes most of its profit in six weeks. December takes more money than August, September and October put together. That pattern is the heart of Paper Lane's problem. The inventory for Christmas is paid for in the autumn, months before it is sold, so the money goes out long before it comes back.

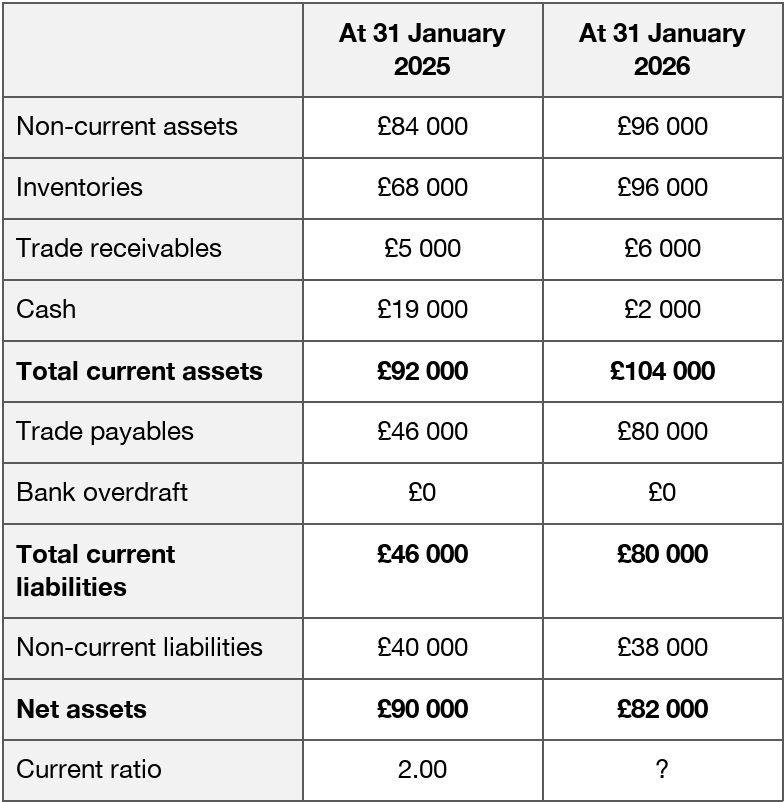
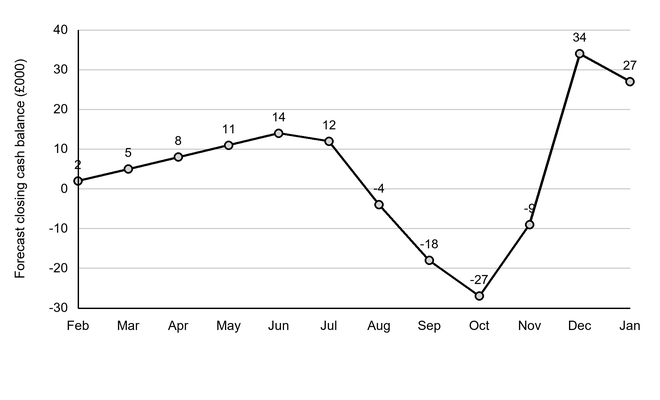
Sales have been steady and the shops are busy. Even so, cash at the bank fell from £19 000 to £2 000 during the year to 31 January 2026, and at its lowest point in the autumn the company was £22 000 into its overdraft. The overdraft limit is £25 000. Appendix D sets out the company's financial position and Appendix E shows what Nina and Rhys forecast will happen to the cash balance over the coming year.

They have been talking about opening a third shop. Their accountant has told them to sort the cash out first. They are also arguing about whether to ask their customers what they actually want, or to trust what nine years behind the counter has taught them.

Appendix D: Paper Lane Ltd summarised statement of financial position

Table comparing Paper Lane Ltd’s financial position at 31 January 2025 and 2026: current assets £92,000/£104,000, current liabilities £46,000/£80,000, net assets £90,000/£82,000; current ratio 2.00 and ?.

Source: Analyst

Appendix E: Paper Lane Ltd forecast closing cash balance, February 2026 to January 2027

Line chart of forecast closing cash balance (£000) from February 2026 to January 2027: 2, 5, 8, 11, 14, 12, −4, −18, −27, −9, 34 and 27 respectively.
  • The company's overdraft limit is £25 000.

Source: Analyst

Paper Lane Ltd went £22 000 into an overdraft with a limit of £25 000 during the year to 31 January 2026.

Analyse one way in which relying on an overdraft might affect Paper Lane Ltd's plan to open a third shop.

7
6 marks

Source B: Center Parcs

Center Parcs runs five holiday villages in the United Kingdom: Sherwood Forest in Nottinghamshire, Elveden Forest in Suffolk, Longleat Forest in Wiltshire, Whinfell Forest in Cumbria and Woburn Forest in Bedfordshire. Woburn Forest, which opened in 2014, is the newest. Guests stay in lodges set in woodland and pay separately for activities, restaurants and the spa.

It is a private limited company, so it has no shares traded on any exchange and no share price. During the 53 weeks to 24 April 2025 it paid dividends of £115.5 million to its owner.

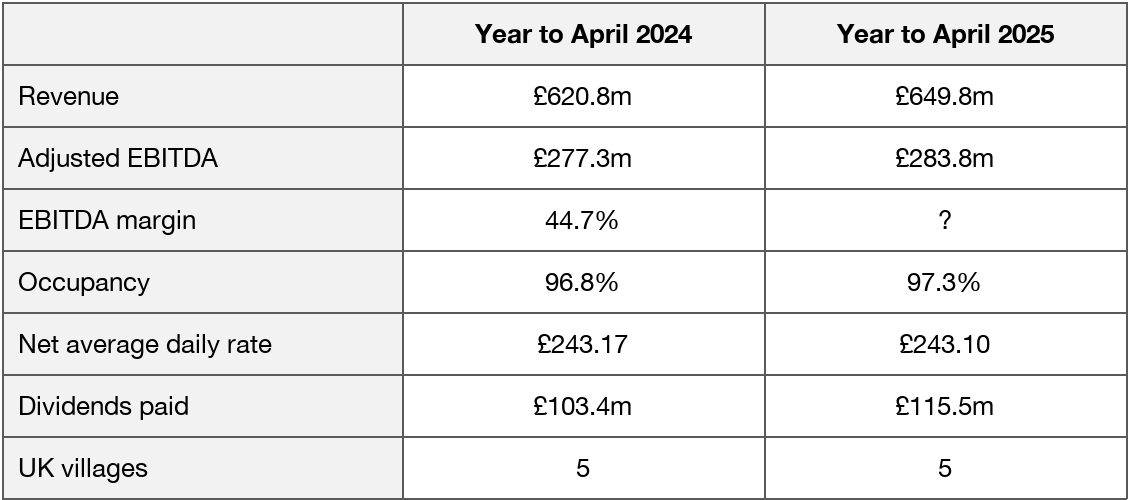
The business is close to full. Occupancy for the year was 97.3%, up from 96.8%, and Appendix E shows that it is not full only in summer: in every month of the year the villages run at or above 93%. Revenue rose 4.7% to £649.8 million and adjusted EBITDA rose to £283.8 million from £277.3 million.

The number that stands still is the price. The net average daily rate was £243.10, against £243.17 the year before. Across a year in which costs rose, Center Parcs took seven pence a night less than it had the year before.

That leaves the company in an unusual position. It cannot sell many more nights, because it has almost no empty ones. It has not raised its daily rate for two years. Growth has therefore had to come from somewhere other than filling lodges or charging more for them, and the directors must decide where the next stage of growth is going to come from. Building a sixth village would take years and a great deal of money. Raising the price would work immediately, if guests accepted it.

Source: information sourced from the Center Parcs (Holdings 1) Limited annual report and financial statements for the 53 weeks ended 24 April 2025, which cover the five UK villages only

Appendix D: Center Parcs selected results

Table comparing Center Parcs results for years to April 2024 and 2025: revenue £620.8m/£649.8m; adjusted EBITDA £277.3m/£283.8m; EBITDA margin 44.7%/?; occupancy 96.8%/97.3%; daily rate £243.17/£243.10; dividends £103.4m/£115.5m; five UK villages.

Source: Center Parcs

Center Parcs is a private limited company, so it has no shares traded on any exchange. Building a sixth village would take years and a great deal of money.

Analyse one way in which being a private limited company might affect how Center Parcs could raise the money for a sixth village.

1
9 marks

Source B: Calder Vale Ceramics Ltd

Calder Vale Ceramics Ltd makes tableware: plates, bowls and serving dishes, thrown and glazed at a single factory in Lancashire. It is a private limited company owned by its two directors, Nadia Okonjo and Rob Hartley, and it employs 19 people.

It does not sell to the public. Its customers are restaurant groups, hotels and independent homeware shops, who order in batches and expect the same glaze to be available again in two years' time. Last year it fired and sold 77 500 pieces at an average price of £16.00, which brought in £1 240 000.

Two kilns do all the work. They cost £14 200 a month to run, staff, maintain and insure, and that is paid whether or not a single piece is fired. A third kiln would cost £180 000 and would let the company take the larger restaurant contracts it currently turns down.

The difficulty is not profit. The difficulty is when the money arrives. Calder Vale Ceramics Ltd's largest customers are restaurant groups, and they take 62 days to pay. Its own clay and glaze come from two small family firms, and Calder Vale Ceramics Ltd pays them within 30 days, because it always has. Finished inventory sits in the warehouse for about seven weeks before a customer calls it off.

Last year it made a gross profit of £558 000 on its £1 240 000 of revenue, once the £682 000 of clay, glaze, packaging and firing was paid for. Wages came to £298 000 and the kiln, factory, insurance and other fixed costs to £170 400, leaving a profit for the year of £89 600. It ended the year with £18 300 in the bank.

Appendix F: Data for two ways of paying for a third kiln

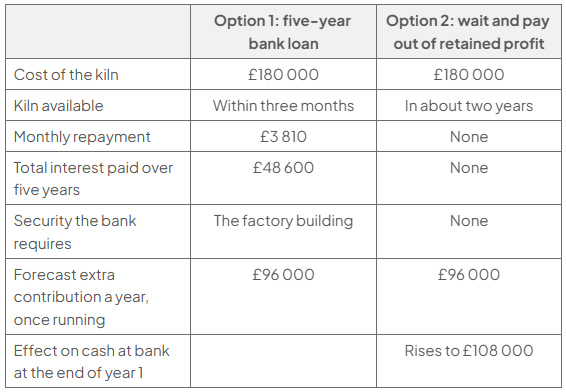
Table comparing two ways to fund a £180 000 kiln. Option 1, a five-year bank loan: kiln available within three months, monthly repayment £3 810, total interest over five years £48 600, security required is the factory building, forecast extra contribution £96 000 a year once running, and the effect on cash at bank at the end of year 1 is not given. Option 2, wait and pay out of retained profit: kiln available in about two years, no repayments, no interest and no security, forecast extra contribution £96 000 a year once running, and cash at bank at the end of year 1 rises to £108 000.

Source: Analyst

Assess whether a five-year bank loan, as set out in Appendix F, would be a suitable way for Calder Vale Ceramics Ltd to pay for a third kiln.

2
9 marks

Source B: Brackenhill Films Ltd

Brackenhill Films Ltd makes documentaries and children's series in Bristol. It is a private limited company with eleven permanent staff: producers, an office manager and two editors. Everyone else is hired for the length of a production.

It does not sell to the public. Broadcasters and streaming services commission a programme, agree a fee and a budget, and Brackenhill Films Ltd delivers it. Last year it delivered four productions for a total of £2 140 000, an average of £535 000 each. The direct costs of making them came to £1 722 000. Fixed overheads, meaning the office, the permanent staff and the edit suites, were £468 000, and they are paid whether a production is in progress or not. The company therefore lost £50 000 on the year.

The budget for each production is agreed with the broadcaster at the start. If a production comes in under budget Brackenhill Films Ltd keeps the difference. If it goes over, Brackenhill Films Ltd pays the difference itself. On the four productions delivered last year the budgets were set by copying the previous year's figures for a similar programme and adding a little for inflation.

Money arrives in three instalments: a third when the programme is commissioned, a third when a rough cut is delivered and a third on final delivery. Costs do not arrive in three instalments. Crews, camera hire and studio time are paid as the work happens, which is why the company's bank balance looks the way it does.

Brackenhill Films Ltd has an overdraft facility of £50 000.

Appendix D: Brackenhill Films Ltd cash at bank, month by month

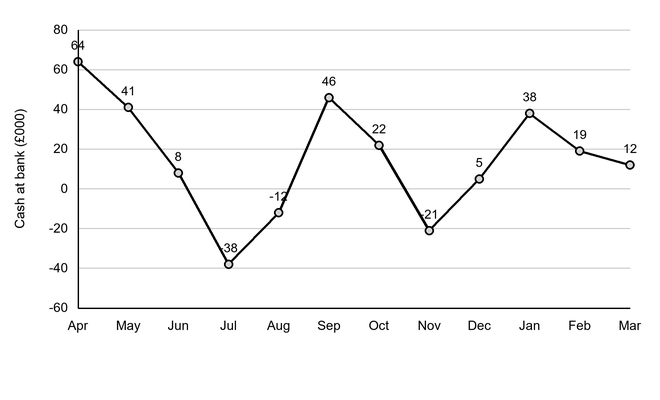
Line chart of monthly cash at bank, in £000, from April to March: values range from £64,000 to negative £38,000, with deficits in July, August and November; y-axis spans −£60,000 to £80,000.

Source: Analyst

Assess whether the cash position shown in Appendix D means an overdraft would be a suitable source of finance for Brackenhill Films Ltd.

3
9 marks

Source B: Halvergate Storage Ltd

Halvergate Storage Ltd rents storage units by the month. It has three sites in East Anglia, at Norwich, King's Lynn and Lowestoft, with 1 200 units between them. It is a private limited company owned by two brothers, Tom and Michael Ferris, and it employs nine people.

Its customers are households between moves, people who have downsized, and small businesses storing inventory. A unit costs an average of £100 a month. Once a unit is let it costs Halvergate Storage Ltd about £12 a month in electricity, cleaning and administration. Everything else is fixed: staff of £290 000 a year and rates, insurance and maintenance of £186 000, which are paid on the whole building whether the units inside it are full or empty.

Last year 80% of the units were let, which is 960 of the 1 200, and revenue was £1 152 000. Operating profit was £537 760. After £152 000 of interest, profit for the year before tax was £385 760.

The interest is there because the sites were built with borrowed money. The three sites together represent capital employed of £4.2 million, of which £2.6 million is long-term bank loans and £1.6 million is the brothers' own money.

Tom and Michael Ferris have set the company an objective: a return on capital employed of 15% within three years. They are also looking at a fourth site, at Bury St Edmunds, which would cost £1.6 million.

Appendix D: Halvergate Storage Ltd, summary of last year

Appendix D summary table lists units, occupancy, rent, revenue, variable and fixed costs, operating profit, interest, pre-tax profit, capital employed and its loan/owner split; return on capital employed is shown as “?”.

Source: Analyst

Appendix F: Data for two ways of paying for a fourth site

Appendix F: both options raise £1.6m. Further bank loan: long-term loans £4.2m, capital employed £5.8m, yearly interest £94,000. Sell and lease Norwich: no change to loans or capital employed, yearly rent £131,000. Gearing after each option is not given.

Source: Analyst

Assess whether a further bank loan, as set out in Appendix F, would be a suitable way for Halvergate Storage Ltd to pay for a fourth site.

4
9 marks

Source B: Marlowe Joinery Ltd

Marlowe Joinery Ltd makes bespoke staircases in a workshop outside Shrewsbury. It is a private limited company run by Gethin Marlowe, the third generation of his family to run it, and it employs 17 people, nine of them joiners who served apprenticeships there.

Every staircase is different. An architect or a builder sends drawings, Gethin Marlowe quotes a price, and if the quote is accepted the workshop builds it. Last year it made 560 staircases at an average price of £2 400, which is revenue of £1 344 000. Timber, fittings and the joiners' time on the job come to £1 560 a staircase. Everything else, meaning the workshop, the machinery, insurance, administration and the wages of people not on a job, comes to £392 000 a year.

The quoting is done by eye. Gethin Marlowe has forty years of it and is good at it, but each quote is its own small budget and nobody adds them up until the year end.

He is considering a computer-controlled cutting machine costing £340 000. It would cut the cost of a staircase to £1 410 and raise the workshop's fixed costs by £68 000 a year once depreciation and finance are counted. It would also lift what the workshop could make in a year from 600 staircases to 900.

The machine would be paid for by borrowing. Marlowe Joinery Ltd already has £280 000 of long-term loans against £620 000 of Gethin Marlowe's own money in the business.

Appendix D: Marlowe Joinery Ltd, summary of last year

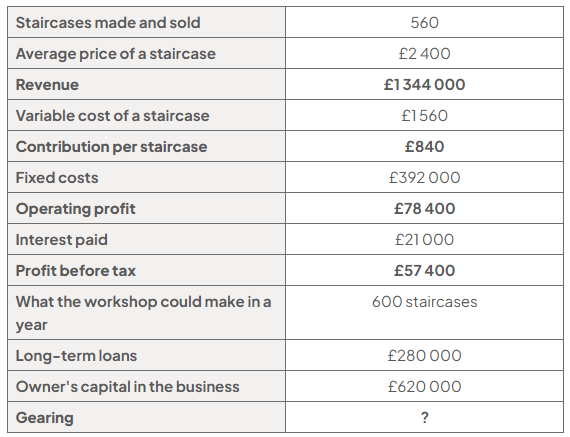
Appendix D summary table: long-term loans are £280,000 and the owner’s capital is £620,000; gearing before new borrowing is shown as “?”.

Source: Analyst

Appendix F: Data for the cutting machine

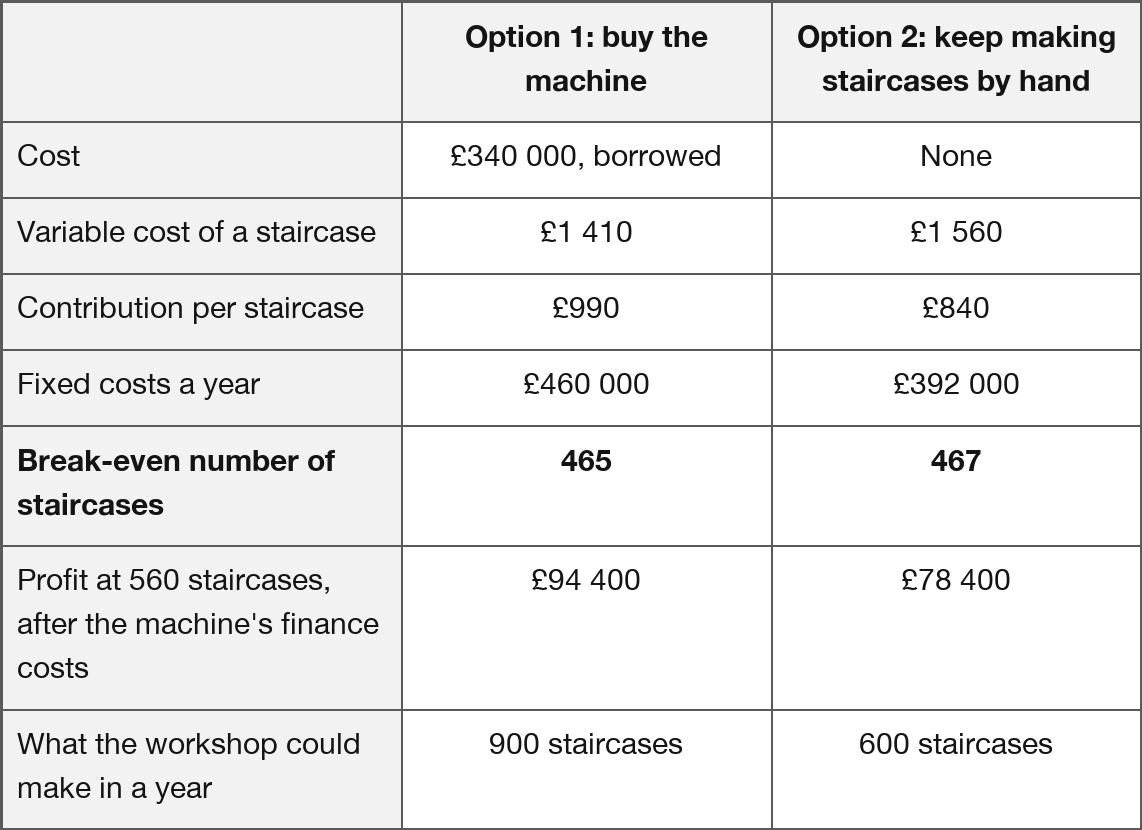
Appendix F comparison table: buying the machine costs £340 000 borrowed; variable cost £1 410, contribution £990, fixed costs £460 000, break-even 465, profit £94 400, capacity 900. By hand: no cost, £1 560, £840, £392 000, 467, £78 400, 600 respectively.

Source: Analyst

Assess whether borrowing the £340 000 shown in Appendix F is a suitable way for Marlowe Joinery Ltd to pay for the cutting machine.

Calculate Marlowe Joinery Ltd's gearing before any new borrowing to support your answer.

Give your answer to one decimal place.

5
9 marks

Source B: Foxhall Creamery Ltd

Foxhall Creamery Ltd makes hard cheese on the Shropshire border. It is a private limited company owned in equal shares by Kate Foxhall, who is 61, and Owen Ridd, who is 58, and it employs 48 people. Revenue last year was £6 800 000, sold to farm shops, delicatessens and independent grocers, none of whom takes more than 4% of output.

The cheese has to sit. The youngest thing Foxhall Creamery Ltd sells has been in the store for nine months, and its best-known cheese comes out at fourteen. Every wheel in the store is money already spent and not yet earned, and there are two rooms of them.

The accounts look reassuring. At the year end the company held £1 240 000 of inventory, was owed £680 000 by customers and had £410 000 in the bank, against £520 000 owed to suppliers, £118 000 in VAT and PAYE, and £194 000 of the bank loan falling due within the year. The loan stands at £1 460 000 in total, and the financial objective for this year is to reduce it by £200 000.

Foxhall Creamery Ltd values the cheese in its store at what the milk, the labour and the power have cost. A wheel that has been maturing for thirteen months appears in the accounts at the same figure as it did on the day it was made, although the price it will fetch has roughly doubled in the meantime.

The company needs a third maturing store, which will cost £900 000. It can pay for it out of the bank balance and this year's retained profit, or it can borrow again.

There is a larger question behind that one. Kate Foxhall wants to retire within five years. A cheese wholesaler has offered £4 900 000 for the company. The alternative the two of them have been reading about is an employee ownership trust, which would buy the business on behalf of the 48 staff and pay Kate Foxhall and Owen Ridd out of future profits over about seven years.

Appendix D: Foxhall Creamery Ltd, current assets and current liabilities

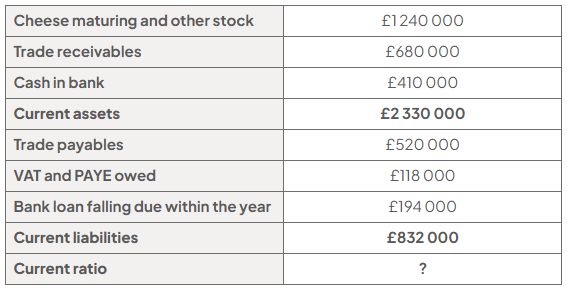
Table of Foxhall Creamery’s current assets and liabilities: inventory £1,240,000, receivables £680,000, cash £410,000, total assets £2,330,000; payables £520,000, VAT and PAYE £118,000, loan due £194,000, total liabilities £832,000. Current ratio: ?

Source: Analyst

Assess whether Foxhall Creamery Ltd should pay for its third maturing store out of its own cash rather than borrowing.

1
15 marks

Source A: Gymshark Ltd

Ben Francis was 19 when he asked his parents if he could use their garage to start making gym clothes he had designed. Whilst studying business at university, Ben teamed up with a school friend, and the gymwear business Gymshark Ltd was born.

Ben used his £5-an-hour wage at Pizza Hut and £1000 savings to invest in equipment like a sewing machine. Ben taught himself to sew and went to bodybuilding events to raise brand awareness. In 2012, Ben dropped out of university to focus on the business full-time.

The Gymshark Ltd brand has become a hit with younger gym goers and is doing well in a highly competitive market. Its competitors include Nike, Adidas and Puma. Instead of using traditional advertising or selling in high street shops, Gymshark Ltd has grown by having athletes and social media 'influencers' wear its clothes on platforms like Instagram, TikTok, and Facebook. Ben is also well known and still shares his own fitness videos online to promote the brand. The company now has 18 million followers on social media.

Gymshark Ltd is a private limited company. In 2021, it raised £200 million by selling shares to a company called General Atlantic. This made Gymshark Ltd one of relatively few British businesses valued at over $1 billion. Ben still owns a 70% stake in the company and has a clear vision of how he wants the business to develop. General Atlantic owns just over 20%. Managers at Gymshark Ltd own 10%. The funds were raised with the aim of expanding the business in North America, where Gymshark Ltd already makes a large part of its sales, and to grow the business rapidly in Asia. Ben has ambitious plans and wants to make the Gymshark Ltd brand the UK equivalent of Nike. The Nike brand was worth $31 billion in 2023 globally; market research suggests that 43% of people who buy Nike sportswear would do so again.

In October 2022, Gymshark Ltd made a significant investment and opened its first physical store on Regent Street in London.

Source: information sourced from Gymshark, 2024

Appendix A: Extracts from Gymshark Group Ltd's statement of financial position as at July 2024

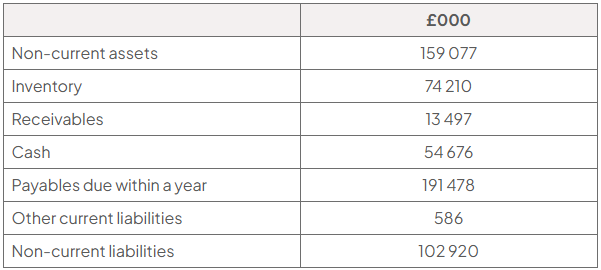
Financial-position table for Gymshark Group Ltd, July 2024 (£000): non-current assets 159,077; inventory 74,210; receivables 13,497; cash 54,676; payables 191,478; other current liabilities 586; non-current liabilities 102,920.

Source: Companies House

Ben Francis has ambitious plans for Gymshark Ltd.

Evaluate two sources of external finance that Ben could use to fund these plans and recommend which one he should choose.

2
15 marks

Source B: Brompton Bicycle Ltd

Brompton Bicycle Limited makes folding bicycles. Andrew Ritchie designed the first one in 1975 and built it in a workshop under a railway arch, and the company was registered the following year. Fifty years on, every Brompton is still made by hand and quality checked at the company's own factory in Greenford, west London. It is a private limited company with around 100 shareholders and is led by chief executive Will Butler-Adams, who joined the company in 2002 and has led it since 2008.

In principle the product has barely changed. A Brompton folds into a small package in under 20 seconds, so an owner can carry it onto a train, put it in a car boot or tuck it under a restaurant table. The range now includes electric, lightweight titanium and larger-wheel models. Brompton describes its purpose as creating urban freedom for happier lives, and it sells durability as part of the deal. Every frame carries a seven-year warranty, the bikes are designed to be repaired rather than replaced, and there are now more than a million Brompton owners and over 300 owners' groups around the world.

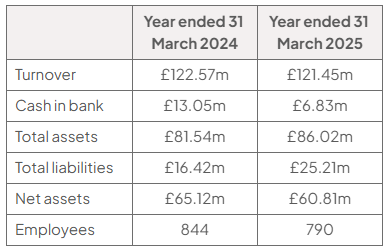
The year to 31 March 2025 was harder than usual. Turnover slipped by 0.9% to £121.45 million, the workforce fell by 54 people to 790, and cash at the bank almost halved. Over the same year the company's total liabilities rose by 53.5%.

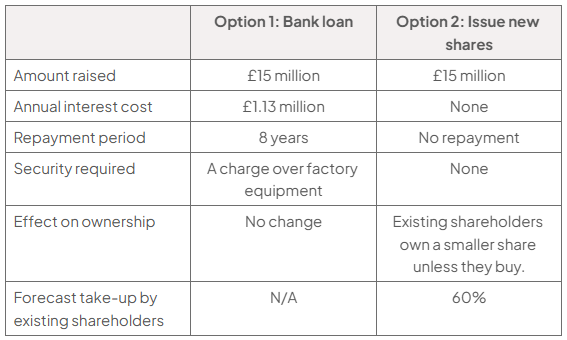
Brompton would like to invest £15 million in its factory so that it can build more bikes at a lower cost per bike. It does not hold enough cash to pay for this out of its own resources. It could borrow the money from a bank, or it could ask its existing shareholders to buy new shares. Appendix F shows information on the two options.

Source: information sourced from Companies House and Brompton Bicycle Ltd, 2026

Appendix D: Brompton Bicycle Ltd selected financial data

Table of selected financial data for 2024 and 2025 respectively: turnover £122.57m, £121.45m; cash £13.05m, £6.83m; assets £81.54m, £86.02m; liabilities £16.42m, £25.21m; net assets £65.12m, £60.81m; employees 844, 790.

Source: Companies House

Appendix F: Data for two ways of raising £15 million

Comparison table for raising £15 million: bank loan: £1.13m annual interest, eight-year repayment, factory equipment security, no ownership change; new shares: no interest or repayment, no security, smaller existing-shareholder ownership, 60% forecast take-up.

Source: Analyst

Appendix F shows two ways in which Brompton Bicycle Ltd could raise £15 million.

Evaluate both options and recommend which one would be the better way for Brompton Bicycle Ltd to raise the £15 million.

3
15 marks

Source B: Paper Lane Ltd

Paper Lane Ltd sells stationery, cards and gifts from two small shops in market towns about 15 miles apart. Nina Okafor and Rhys Pritchard opened the first shop nine years ago and set the business up as a private limited company, with the two of them as the only directors and shareholders. They now employ nine other people, most of them part time.

The shops sell notebooks, pens, wrapping paper, cards and small gifts. Customers come in to browse, and a large share of what they buy was not on a list when they walked through the door. Nina and Rhys buy most of their inventory from small makers and from two wholesalers, and they order the Christmas range in August to get an 8% early order discount.

The business makes most of its profit in six weeks. December takes more money than August, September and October put together. That pattern is the heart of Paper Lane's problem. The inventory for Christmas is paid for in the autumn, months before it is sold, so the money goes out long before it comes back.

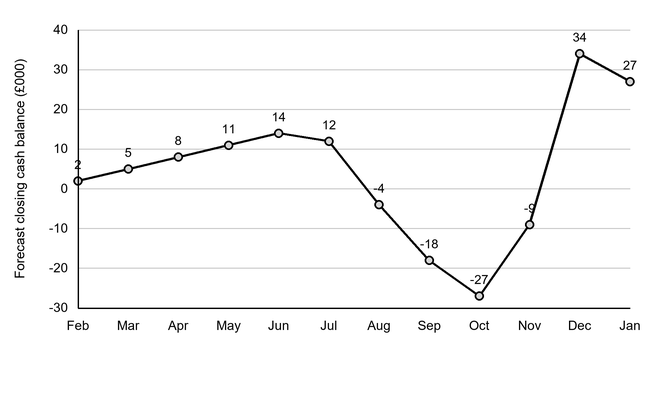
Sales have been steady and the shops are busy. Even so, cash at the bank fell from £19 000 to £2 000 during the year to 31 January 2026, and at its lowest point in the autumn the company was £22 000 into its overdraft. The overdraft limit is £25 000. Appendix D sets out the company's financial position and Appendix E shows what Nina and Rhys forecast will happen to the cash balance over the coming year.

They have been talking about opening a third shop. Their accountant has told them to sort the cash out first. They are also arguing about whether to ask their customers what they actually want, or to trust what nine years behind the counter has taught them.

Appendix D: Paper Lane Ltd summarised statement of financial position

Table comparing Paper Lane Ltd’s financial position at 31 January 2025 and 2026: current assets £92,000/£104,000, current liabilities £46,000/£80,000, net assets £90,000/£82,000; current ratio 2.00 and ?.

Source: Analyst

Appendix E: Paper Lane Ltd forecast closing cash balance, February 2026 to January 2027

Line chart of forecast closing cash balance (£000) from February 2026 to January 2027: 2, 5, 8, 11, 14, 12, −4, −18, −27, −9, 34 and 27 respectively; lowest in October, highest in December.

The company's overdraft limit is £25 000.

Source: Analyst

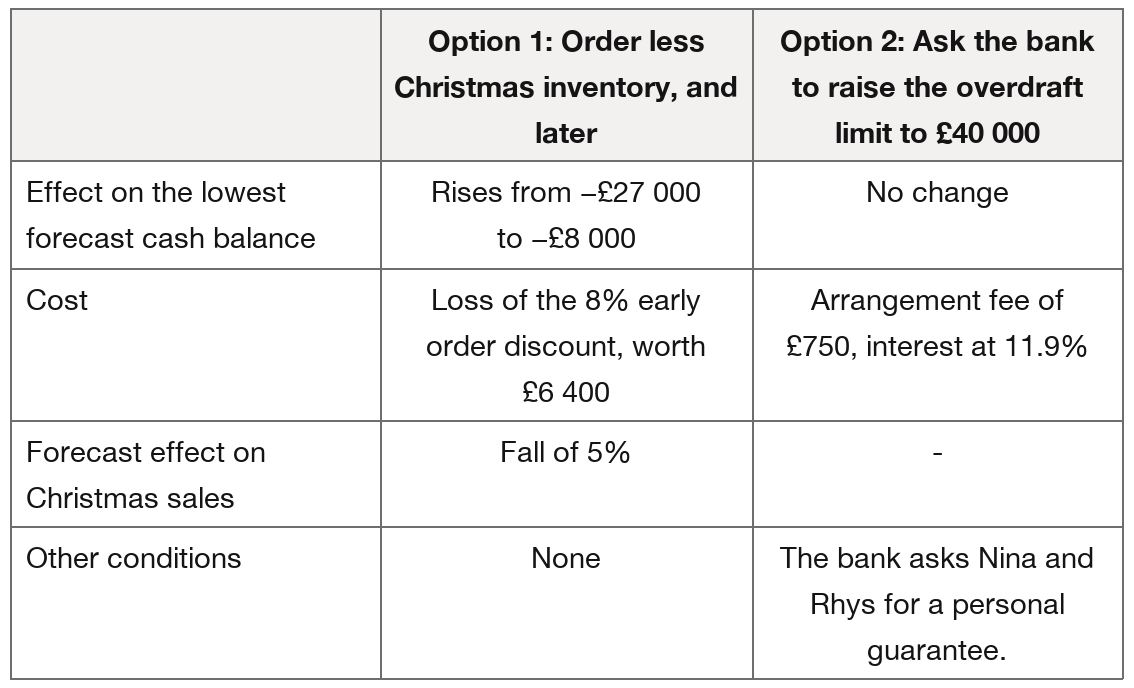
Appendix F: Data for two ways of dealing with the autumn cash shortage

Comparison table: Option 1 reduces the cash low from −£27,000 to −£8,000 but loses a £6,400 discount and 5% of Christmas sales. Option 2 raises the overdraft to £40,000, costing £750 plus 11.9% interest and a personal guarantee.

Source: Analyst

Appendix F shows two ways of dealing with Paper Lane Ltd's autumn cash shortage.

Evaluate both options and recommend which one would be the better way for Paper Lane Ltd to deal with the shortage.