The Marketing Mix (AQA A Level Business): Exam Questions

Exam code: 7132

Syllabus Edition

First teaching 2026

First exams 2028

2 hours17 questions
1
6 marks

Source B: Apple's Vision Pro

In September 2023, Apple launched the Vision Pro in North America. Vision Pro is a virtual reality (VR) headset. Unlike rival headsets which require hand-held controllers, Vision Pro is controlled by hand movements, voice commands and eye tracking. Analysts estimated over $8 billion had been spent developing Vision Pro over five years.

The Vision Pro may turn out to be one of Apple's lowest-selling products. Apple reportedly hoped to sell 3 million units in the first year. Some experts expected sales would be below 200,000 units in this period, lower than any of Apple's other major product launches. Others were more optimistic about Vision Pro's long-term sales. Apple set a high price of $3499. This price was three times more expensive than Meta's competing headset, the Quest. Other issues with the product included a battery that lasted only two hours and a headset that some users said was awkward to wear.

Apple was keen to release the Vision Pro because of strong competition, especially from Meta. Meta had been selling the Quest at a loss to increase its market share.

Steve Jobs, Apple's founder, once said that customers do not know what they want until Apple makes it.

Over 2 billion Apple devices are in use around the world. Apple also has:

  • a huge database of information about current users of its products.

  • a wide product portfolio including iPads, Mac computers, iPods, Apple TV, and the Apple watch.

  • a trusted brand. In a 2021 survey, three times as many people said they would buy a headset from Apple compared to its closest competitor.

In 2023, Apple increased its dividend payments to about 15% of its yearly profits.

Source: Apple, 2024

Apple often sets a high price for its products, such as Vision Pro, compared to its competitors.

Analyse one way in which setting a high price might affect the revenue Apple earns from its products.

2
6 marks

Source A: Greggs plc

Greggs plc is the UK's largest food-to-go retailer. It began as a single bakery in Newcastle upon Tyne and floated on the London Stock Exchange in 1984. It is now part of the FTSE 250 and is led by chief executive Roisin Currie.

Greggs sells sausage rolls, bakes, sandwiches, hot drinks and sweet items at prices deliberately set below those of most high street rivals. It calls itself a value retailer, but says that value comes from quality as well as price, and points to freshly prepared food, hot options and the ability for customers to customise their order. In December 2025 it held 8.6% of all visits in the UK food-to-go market and was rated the country's leading food-to-go brand.

The business has grown by making itself easier to reach. It opened 121 net new shops in 2025, ending the year with 2 739, and says there is a clear opportunity for significantly more than 3 000 UK shops in the longer term. Alongside the shops it has pushed three other ways to reach the customer. Delivery now accounts for 6.8% of sales in company-managed shops. Evening trade is the fastest growing part of the day. The Greggs App was scanned in 26.7% of transactions in 2025, up from 20.1% in 2024, and customers who use the App shop at Greggs more often. The company has also started selling through grocers, launching a Bake-at-Home range with Tesco and widening its range in Iceland.

That growth has been expensive. Capital spending peaked at £287.5 million in 2025 as Greggs built two new national distribution centres, at Derby and Kettering, lifting its logistics capacity to 3 500 shops. Capital spending is expected to fall to around £200 million in 2026. Greggs also made £13.0 million of structural cost savings during 2025 and holds a net cash position of £45.8 million.

The company says its key focus is restoring its return on capital employed to a target of around 20%.

Source: Greggs plc preliminary results, 3 March 2026

Greggs plc sets its prices below those of most of its high street rivals.

Analyse one way in which this pricing decision might affect Greggs plc's sales revenue.

3
6 marks

Source B: Brompton Bicycle Ltd

Brompton Bicycle Limited makes folding bicycles. Andrew Ritchie designed the first one in 1975 and built it in a workshop under a railway arch, and the company was registered the following year. Fifty years on, every Brompton is still made by hand and quality checked at the company's own factory in Greenford, west London. It is a private limited company with around 100 shareholders and is led by chief executive Will Butler-Adams, who joined the company in 2002 and has led it since 2008.

In principle the product has barely changed. A Brompton folds into a small package in under 20 seconds, so an owner can carry it onto a train, put it in a car boot or tuck it under a restaurant table. The range now includes electric, lightweight titanium and larger-wheel models. Brompton describes its purpose as creating urban freedom for happier lives, and it sells durability as part of the deal. Every frame carries a seven-year warranty, the bikes are designed to be repaired rather than replaced, and there are now more than a million Brompton owners and over 300 owners' groups around the world.

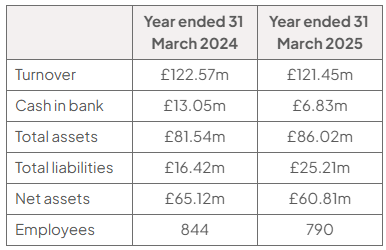
The year to 31 March 2025 was harder than usual. Turnover slipped by 0.9% to £121.45 million, the workforce fell by 54 people to 790, and cash at the bank almost halved. Over the same year the company's total liabilities rose by 53.5%.

Brompton would like to invest £15 million in its factory so that it can build more bikes at a lower cost per bike. It does not hold enough cash to pay for this out of its own resources. It could borrow the money from a bank, or it could ask its existing shareholders to buy new shares.

Source: information sourced from Companies House and Brompton Bicycle Ltd, 2026

Every Brompton frame carries a seven-year warranty.

Analyse one way in which this warranty could affect Brompton Bicycle Ltd's competitiveness.

4
6 marks

Source B: Big Issue Media Ltd

Big Issue Media Limited publishes The Big Issue, a weekly magazine sold on the street by people who are homeless or at risk of becoming homeless. The company was set up in 1991 and is part of a group of 16 companies known as the Big Issue Group. It is a social enterprise: it trades like any other business, but it exists to create work for its vendors rather than to pay outside shareholders.

The selling model is unusual. Vendors buy copies of the magazine from Big Issue Media Limited at half the cover price, then sell them at the full price and keep the difference. A vendor is not an employee. What they earn depends entirely on how many copies they sell, so the number of magazines moving through the business is also the number that decides whether a vendor can pay their rent.

That number has been falling. Fewer people carry cash, fewer people buy print magazines, and the streets are quieter than they were. In the year to 31 March 2025 turnover fell by 37.1% to £3.92 million. The company cut its workforce from 74 people to 56. Cash at the bank fell to £297 000 and net assets fell by 43.6% to £630 000. Appendix D shows how the business changed.

The directors are considering two ways forward. They could raise the cover price, which would give each vendor more money for every copy sold. Or they could push more sales through the Big Issue app and website, which costs less to run but cuts the vendors out of the sale.

Source: information sourced from Companies House, 2026

Vendors buy copies of The Big Issue at half the cover price and sell them at the full price, keeping the difference.

Analyse one way in which selling through vendors rather than through shops might affect Big Issue Media Ltd's costs.

5
6 marks

Source B: Home Instead Ltd

Home Instead Limited arranges care for older people in their own homes: help with washing and dressing, meals, medication, shopping and company. It has been trading in the United Kingdom since 2005 from an office near Warrington, and it is owned by an American company.

Home Instead does not provide the care itself. It is a franchisor. Local business owners buy the right to run a Home Instead office in a particular area, and in return they use the name, the training and the systems, and pay a fee on everything they sell. Those franchisees recruit and employ the carers. This is why the company's accounts look so unusual for a care business: turnover of £19.5 million but only 64 employees, because almost everybody who does the work is employed by somebody else.

The market is growing. The Office for National Statistics projects that the number of people in the UK at state pension age will rise from 12.0 million in mid-2022 to 13.7 million by mid-2032, an increase of 13.8%, while the population as a whole grows by 7.3%. Older people are becoming a larger share of the country, and most of them would prefer to stay in their own homes.

The company's own finances moved in two directions during 2025. Turnover rose 7.9% to £19.5 million. But cash at the bank fell by 28.8% to £3.12 million and net assets fell by 10.8% to £5.10 million.

Home Instead now has a choice about how to grow. It could recruit more franchisees to cover the areas it does not reach. Or it could buy back some territories and run them itself, employing the carers directly.

Source: information sourced from Companies House and the Office for National Statistics, 2026

Home Instead Ltd's franchisees employ the carers and deal with the clients, but the name, the training and the systems belong to Home Instead Ltd.

Analyse one way in which this might affect Home Instead Ltd's ability to build a strong brand.

6
6 marks

Source B: Home Instead Ltd

Home Instead Limited arranges care for older people in their own homes: help with washing and dressing, meals, medication, shopping and company. It has been trading in the United Kingdom since 2005 from an office near Warrington, and it is owned by an American company.

Home Instead does not provide the care itself. It is a franchisor. Local business owners buy the right to run a Home Instead office in a particular area, and in return they use the name, the training and the systems, and pay a fee on everything they sell. Those franchisees recruit and employ the carers. This is why the company's accounts look so unusual for a care business: turnover of £19.5 million but only 64 employees, because almost everybody who does the work is employed by somebody else.

The market is growing. The Office for National Statistics projects that the number of people in the UK at state pension age will rise from 12.0 million in mid-2022 to 13.7 million by mid-2032, an increase of 13.8%, while the population as a whole grows by 7.3%. Older people are becoming a larger share of the country, and most of them would prefer to stay in their own homes.

The company's own finances moved in two directions during 2025. Turnover rose 7.9% to £19.5 million. But cash at the bank fell by 28.8% to £3.12 million and net assets fell by 10.8% to £5.10 million.

Home Instead now has a choice about how to grow. It could recruit more franchisees to cover the areas it does not reach. Or it could buy back some territories and run them itself, employing the carers directly.

Source: information sourced from Companies House and the Office for National Statistics, 2026

Home Instead Ltd needs local business owners to buy franchises before it can open in a new area.

Analyse one way in which promoting to possible franchisees might differ from promoting to the families who buy care.

7
6 marks

Source B: Brightpath Learning Ltd

Brightpath Learning Ltd is an online tutoring company set up six years ago by two former teachers, Aisha Rahman and Tom Petridis, who are its only shareholders and directors. It employs 31 people at its office in Leeds and works with about 400 self-employed tutors.

It sells two quite different things.

Live tutoring. A student books one-to-one lessons online with a subject specialist. A lesson costs the parent £38. Brightpath pays the tutor £26 and keeps £12. This is the larger part of the business and the part parents ask for by name, but it can only grow as fast as Brightpath can recruit and check tutors, and a tutor can only teach one student at a time.

The practice platform. A subscription costs £9 a month and gives a student unlimited access to Brightpath's own question banks, marked practice papers and progress tracking. It costs almost nothing to serve one more subscriber, because the material is already written. Fewer parents ask for it, because it is harder to explain than a lesson with a teacher.

Last year Brightpath took £7.4 million: £6.5 million from tutoring and £0.9 million from subscriptions. Fixed costs, covering the office, the 31 staff, the software and the marketing, came to £1.9 million.

The business is highly seasonal. Appendix E shows lessons booked month by month: demand builds through the autumn, rises sharply after Christmas and peaks in April, then collapses once exams finish. Aisha and Tom have to pay the office and the staff through June, July and August whatever happens.

They now have to decide where to put next year's money. Appendix F sets out the two options.

Brightpath Learning Ltd works with about 400 self-employed tutors rather than employing them.

Analyse one way in which this might affect whether Brightpath Learning Ltd's customers book lessons with it again.

8
6 marks

Source A: Bunzl plc

Bunzl plc is a distribution and services group. It does not make much: it buys products from manufacturers, holds them, and delivers them to businesses that need them regularly but do not want to manage the supply themselves. Its customers are in cleaning and hygiene, safety, healthcare, foodservice and grocery, and they are spread across more than 30 countries.

A hospital does not want to negotiate with forty suppliers for gloves, wipes and aprons. Bunzl sells it one relationship. That is the business.

The year to 31 December 2024 produced an odd set of numbers. Revenue was £11 776.4 million against £11 797.1 million, which is a fall of 0.2%. But at constant exchange rates, which strips out the effect of the pound moving against other currencies, revenue rose 3.1%. Adjusted operating profit rose 3.4% as reported and 7.2% at constant rates. Appendix B shows the two measures side by side.

The operating margin improved, from 8.0% to 8.3%. Bunzl puts that down partly to selling more of its own brand products, which it sources itself rather than buying from a manufacturer whose name is on the box, and partly to the businesses it has bought.

Buying businesses is how Bunzl grows. During 2024 it completed 15 acquisitions, 13 of them announced, and committed a record £883 million to them. Those businesses are expected to add £744 million of revenue and £72 million of adjusted operating profit in a full year.

Adjusted earnings per share reached 194.3p and the dividend rose 8.2% to 73.9p. Cash conversion was 93%.

Source: information sourced from Bunzl plc annual results for the year ended 31 December 2024

Appendix C: Own brand and branded products, analyst estimates

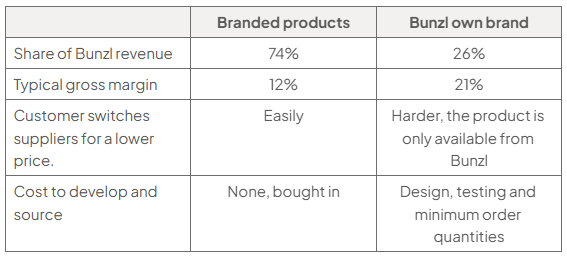
Table comparing branded products with Bunzl own brand: revenue share 74% versus 26%; typical gross margin 12% versus 21%; customers switch suppliers easily versus with difficulty; costs are bought in versus design, testing and minimum orders.

Source: Analyst

Bunzl plc sells own brand products alongside products made by other manufacturers.

Analyse one way in which selling more own brand products might affect Bunzl plc's gross margin.

9
6 marks

Source B: Dunelm Group plc

Dunelm Group plc sells homewares and furniture: curtains, bedding, cookware, lighting, storage, sofas. It is a public limited company and it sells through large out-of-town stores and through its website and app.

In the year to 28 June 2025 revenue rose 3.8% to £1.77 billion and profit before tax rose 2.7% to £211 million, with the margin slipping slightly to 11.9%. Its share of the combined homewares and furniture market rose from 7.7% to 7.9%, and the number of active customers, meaning people who have bought something within the last year, rose slightly.

The change underneath those figures is where the customer shops. Digital sales are now 40% of everything Dunelm sells, up from 37% the year before. Appendix E shows how that share has moved over five years.

The complication is that digital and stores are not two separate businesses with two separate customers. The same person browses online and buys in store, or measures an item in store and orders at home, or buys online and returns to a store. A sofa is rarely bought without being sat on. A set of tea towels rarely needs a visit. Dunelm has to work out what a customer actually wants from each part of the business, when that customer does not think of them as separate at all.

It now has to decide where the next investment goes. Appendix F sets out the options.

Source: information sourced from Dunelm Group plc preliminary results for the year ended 28 June 2025

A Dunelm customer will rarely buy a sofa without sitting on it, but will happily buy tea towels without visiting a store.

Analyse one way in which this might affect the range of products Dunelm Group plc chooses to promote online.

1
9 marks

Source A: Gymshark Ltd

Ben Francis was 19 when he asked his parents if he could use their garage to start making gym clothes he had designed. Whilst studying business at university, Ben teamed up with a school friend, and the gymwear business Gymshark Ltd was born.

Ben used his £5-an-hour wage at Pizza Hut and £1000 savings to invest in equipment like a sewing machine. Ben taught himself to sew and went to bodybuilding events to raise brand awareness. In 2012, Ben dropped out of university to focus on the business full-time.

The Gymshark Ltd brand has become a hit with younger gym goers and is doing well in a highly competitive market. Its competitors include Nike, Adidas and Puma. Instead of using traditional advertising or selling in high street shops, Gymshark Ltd has grown by having athletes and social media 'influencers' wear its clothes on platforms like Instagram, TikTok, and Facebook. Ben is also well known and still shares his own fitness videos online to promote the brand. The company now has 18 million followers on social media.

Gymshark Ltd is a private limited company. In 2021, it raised £200 million by selling shares to a company called General Atlantic. This made Gymshark Ltd one of relatively few British businesses valued at over $1 billion. Ben still owns a 70% stake in the company and has a clear vision of how he wants the business to develop. General Atlantic owns just over 20%. Managers at Gymshark Ltd own 10%. The funds were raised with the aim of expanding the business in North America, where Gymshark Ltd already makes a large part of its sales, and to grow the business rapidly in Asia. Ben has ambitious plans and wants to make the Gymshark Ltd brand the UK equivalent of Nike. The Nike brand was worth $31 billion in 2023 globally; market research suggests that 43% of people who buy Nike sportswear would do so again.

In October 2022, Gymshark Ltd made a significant investment and opened its first physical store on Regent Street in London.

Source: information sourced from Gymshark, 2024

Appendix C: Social networks by number of monthly active users globally, 2024

  • Facebook: 3.0 billion users, with the highest proportion of users aged 25 to 34

  • Instagram: 2.0 billion users, with the highest proportion of users aged 25 to 34

  • TikTok: 1.6 billion users, with the highest proportion of users aged 18 to 24

Source: Statista, 2024

Assess whether increasing spending on influencers would lead to higher profits for Gymshark Ltd.

2
9 marks

Source B: Apple's Vision Pro

In September 2023, Apple launched the Vision Pro in North America. Vision Pro is a virtual reality (VR) headset. Unlike rival headsets which require hand-held controllers, Vision Pro is controlled by hand movements, voice commands and eye tracking. Analysts estimated over $8 billion had been spent developing Vision Pro over five years.

The Vision Pro may turn out to be one of Apple's lowest-selling products. Apple reportedly hoped to sell 3 million units in the first year. Some experts expected sales would be below 200,000 units in this period, lower than any of Apple's other major product launches. Others were more optimistic about Vision Pro's long-term sales. Apple set a high price of $3499. This price was three times more expensive than Meta's competing headset, the Quest. Other issues with the product included a battery that lasted only two-hours and a headset that some users said was awkward to wear.

Apple was keen to release the Vision Pro because of strong competition, especially from Meta. Meta had been selling the Quest at a loss to increase its market share.

Steve Jobs, Apple's founder, once said that customers do not know what they want until Apple makes it.

Over 2 billion Apple devices are in use around the world. Apple also has:

  • a huge database of information about current users of its products.

  • a wide product portfolio including iPads, Mac computers, iPods, Apple TV, and the Apple watch.

  • a trusted brand. In a 2021 survey, three times as many people said they would buy a headset from Apple compared to its closest competitor.

In 2023, Apple increased its dividend payments to about 15% of its yearly profits.

Source: Apple, 2024

Appendix D: Selected financial data for Apple in 2021 and 2023

  • Sales: $365 817 million in 2021, rising to $394 328 million in 2023

  • Operating profit: $108 949 million in 2021, rising to $125 344 million in 2023

  • Investment in new product development: $21 914 million in 2021, rising to $29 915 million in 2023

Source: Apple, 2024

Appendix F: Apple sales by product, 2003 - 2023

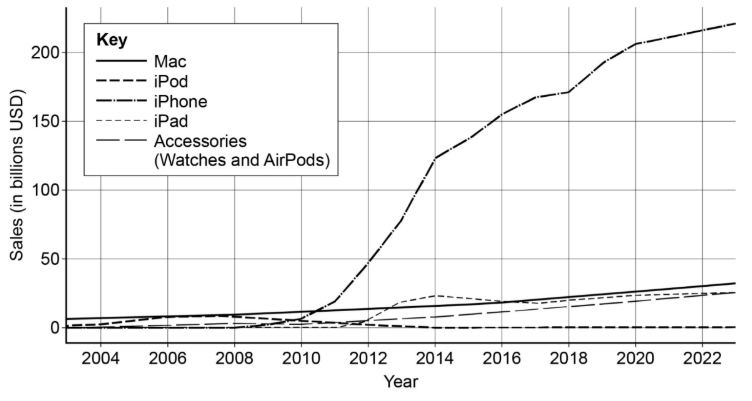
Line graph of Apple sales by product, 2003–2023, in billions of US dollars: iPhone sales rise to about $220bn, while Mac, iPad and accessories remain below $35bn and iPod sales fall to near zero.

Assess whether a large investment in new product development is likely to increase Apple's market share.

3
9 marks

Source A: Meadowbank Pet Foods Ltd

Meadowbank Pet Foods Ltd makes dry dog food at a single factory in Shropshire. It is a private limited company owned by Ros Calderwood, who started it after eleven years as a vet, and it employs 34 people.

It does not sell in supermarkets and has never wanted to. Its food reaches customers through independent pet shops, veterinary practices and its own website, where about a third of customers buy on a repeating subscription. A 12 kilogram bag costs £48. Supermarket own label sells at around £22 for the same weight, and the mid-range brands sit between the two.

What the company sells is an explanation. Every bag lists the percentage of each ingredient, names the farm the meat came from and carries a batch number that a customer can look up. Ros Calderwood's view is that people who read the label are the only customers worth having, because they are the ones who do not switch when a rival runs a promotion.

Last year Meadowbank Pet Foods Ltd took £9.02 million, up from £8.20 million. Almost all of it is still British: £8.06 million against £7.71 million the year before. The two export markets are small and growing quickly. Ireland went from £0.38 million to £0.62 million and the Netherlands from £0.11 million to £0.34 million, both sold through independent pet shops in the same way as at home.

Ros Calderwood has £400 000 to spend and two ways to spend it. She has been offered a distributor in Germany, which is one of the largest pet food markets in Europe and one Meadowbank Pet Foods Ltd has never sold into. Or she can spend the money at home, where growth has slowed to 4.5% and where nine tenths of the revenue already is.

Before deciding anything she ran a test. For three months the price of the 12 kilogram bag went up from £48 to £52, and she watched what happened to the number of bags sold.

Assess whether listing every ingredient and naming the farm the meat came from is likely to increase Meadowbank Pet Foods Ltd's sales.

4
9 marks

Source A: Nine Acres Kitchen Ltd

Nine Acres Kitchen Ltd delivers meal kits: a box of measured ingredients and a recipe card for each meal. It is a private limited company founded by Dan Ferreira and Aisha Nkemelu, it employs 210 people across a packing site in Northamptonshire and an office in Manchester, and it has 12 600 active subscribers.

A subscriber chooses their meals on an app each week. The standard box costs £48.99 and the average subscriber takes two a month, which gives revenue of £14.8 million a year. Ingredients, packing and delivery cost £31.20 a box.

Getting people to try it is not the problem. The first box costs £14.99, and the offer works: the company recruits about 1 400 new subscribers a month. Keeping them is a different matter. Appendix B shows what happens to every hundred people who join. By the fourth box, the third charged at the full £48.99, 41 of them have gone.

The company knows a great deal about all of this. The app records what each subscriber cooks, what they skip, when they pause and what they were looking at before they cancelled. Dan Ferreira wants to use it to work out who is about to leave so the company can offer them something. Aisha Nkemelu wants to use it to suggest what they might cook next, on the grounds that people who enjoy the food do not cancel.

There is a third thing neither of them has raised at a board meeting. Starting a subscription takes about two minutes on the app. Cancelling one requires a telephone call, on weekdays between nine and five.

Appendix A: Nine Acres Kitchen Ltd, last year

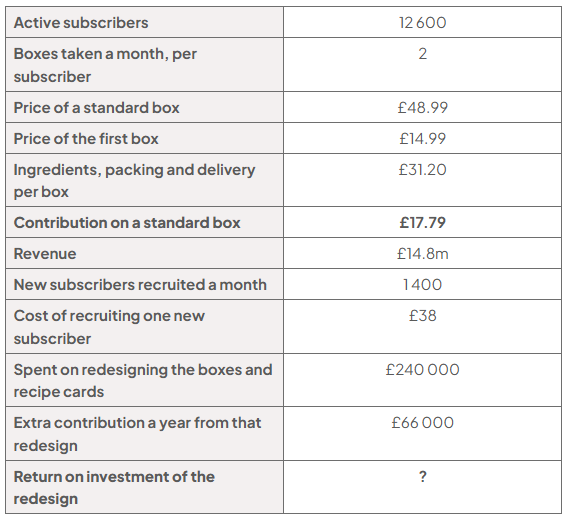
Appendix A table: the redesign generated an extra contribution of £66,000 a year; the return on investment is shown as “?” for the student to calculate.

Source: Analyst

Assess whether Nine Acres Kitchen Ltd was right to spend £240 000 on redesigning its boxes and recipe cards.

Calculate the return on investment of the redesign to support your answer.

Give your answer to one decimal place.

5
9 marks

Source B: Brompton Bicycle Ltd

Brompton Bicycle Limited makes folding bicycles. Andrew Ritchie designed the first one in 1975 and built it in a workshop under a railway arch, and the company was registered the following year. Fifty years on, every Brompton is still made by hand and quality checked at the company's own factory in Greenford, west London. It is a private limited company with around 100 shareholders and is led by chief executive Will Butler-Adams, who joined the company in 2002 and has led it since 2008.

In principle the product has barely changed. A Brompton folds into a small package in under 20 seconds, so an owner can carry it onto a train, put it in a car boot or tuck it under a restaurant table. The range now includes electric, lightweight titanium and larger-wheel models. Brompton describes its purpose as creating urban freedom for happier lives, and it sells durability as part of the deal. Every frame carries a seven-year warranty, the bikes are designed to be repaired rather than replaced, and there are now more than a million Brompton owners and over 300 owners' groups around the world.

The year to 31 March 2025 was harder than usual. Turnover slipped by 0.9% to £121.45 million, the workforce fell by 54 people to 790, and cash at the bank almost halved. Over the same year the company's total liabilities rose by 53.5%.

Brompton would like to invest £15 million in its factory so that it can build more bikes at a lower cost per bike. It does not hold enough cash to pay for this out of its own resources. It could borrow the money from a bank, or it could ask its existing shareholders to buy new shares. Appendix F shows information on the two options.

Source: information sourced from Companies House and Brompton Bicycle Ltd, 2026

Appendix D: Brompton Bicycle Ltd selected financial data

Table comparing years ended 31 March 2024 and 2025: turnover £122.57m/£121.45m; cash £13.05m/£6.83m; assets £81.54m/£86.02m; liabilities £16.42m/£25.21m; net assets £65.12m/£60.81m; employees 844/790.

Source: Companies House

Appendix E: Analyst estimates of pricing for the Brompton C Line model

  • Average selling price, 2024 = £1 650

  • Average selling price, 2025 = £1 815

  • C Line bicycles sold, 2024 = 38 000

  • C Line bicycles sold, 2025 = 36 480

Source: Analyst

Assess the importance of price, compared with the other elements of the marketing mix, in Brompton Bicycle Ltd's ability to sell its folding bicycles.

1
15 marks

Source A: Jet2 plc

Jet2 plc describes itself as the UK's leading provider of package holidays and its third largest airline. It is a public limited company with shares traded on the London Stock Exchange, based at Leeds Bradford Airport, and it employs more than 14 000 people. Steve Heapy is the chief executive.

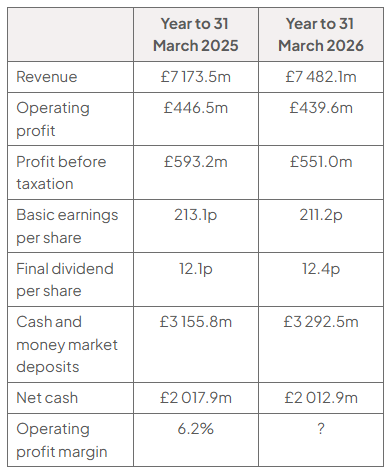
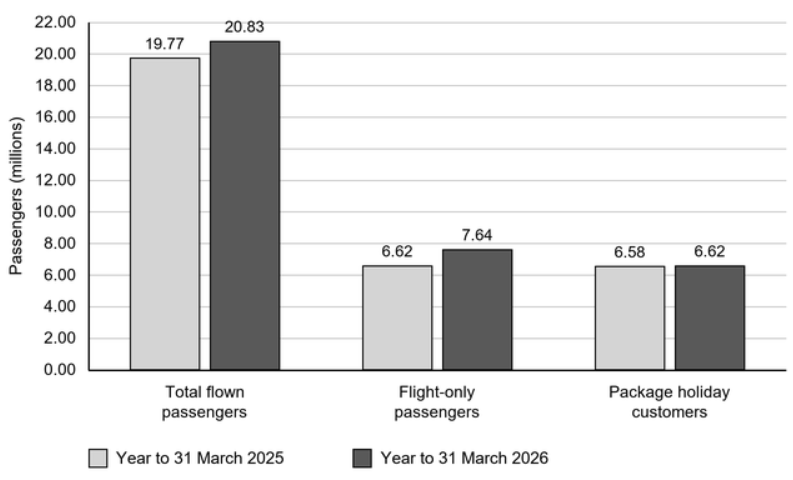
The company sells two different things. A package holiday combines flights, a hotel and transfers in one booking. A flight-only seat is just the flight. In the year to 31 March 2026 Jet2 flew a record 20.83 million passengers, up 5%. Within that total, flight-only passengers rose 15% to 7.64 million while package holiday customers rose 1% to 6.62 million. Jet2 counts each package holiday customer once, while flown passengers are counted on every flight, outbound and return. Appendix B shows the two side by side.

Customers pay for a holiday months before they take it, so money arrives long before the flight happens. At the year end the company held £3 292.5 million in cash and money market deposits, and net cash of £2 012.9 million.

The year's results were mixed. Revenue reached a record £7 482.1 million, up 4%. But operating profit fell 2% to £439.6 million, after absorbing £11.0 million of start-up costs for a new base at London Gatwick and £50 million of increased costs from employment taxes and sustainable aviation fuel. Profit before tax fell 7% and earnings per share fell 1% to 211.2p.

Source: Jet2 plc preliminary results, 8 July 2026, and Companies House

Appendix A: Jet2 plc selected financial results

Appendix A table comparing years to 31 March 2025 and 2026: revenue £7,173.5m/£7,482.1m; operating profit £446.5m/£439.6m; profit before tax £593.2m/£551.0m; EPS 213.1p/211.2p; dividend 12.1p/12.4p; cash £3,155.8m/£3,292.5m; net cash £2,017.9m/£2,012.9m; operating profit margin 6.2%/?.

Appendix B: Jet2 plc passengers by type

Bar chart of Jet2 passengers in millions for years to 31 March 2025 and 2026: total 19.77 to 20.83, flight-only 6.62 to 7.64, and package holidays 6.58 to 6.62. Y-axis ranges from 0 to 22 million.

Appendix C: Jet2 plc marketing information for the year to 31 March 2026

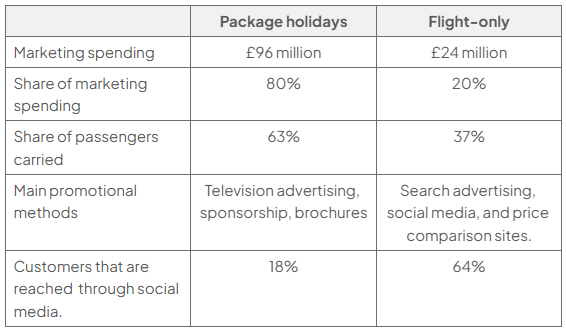
Appendix C table comparing package holidays and flight-only: spending £96m/£24m; spending share 80%/20%; passenger share 63%/37%; social-media reach 18%/64%. Methods: television, sponsorship and brochures versus search, social media and price-comparison sites.

Source: Analyst

Appendix C shows how Jet2 plc's marketing spending is divided between package holidays and flight-only seats.

Evaluate whether Jet2 plc should move more of its marketing spending towards flight-only seats or keep it weighted towards package holidays.

2
15 marks

Source A: Skylark Adventure Ltd

Skylark Adventure Ltd runs six indoor adventure parks, in converted warehouses on the edges of northern towns. Each one has climbing walls, trampolines, an obstacle course and a café. It is a private limited company owned by Ben Attah and Priya Shergill, who opened the first site in 2016, and it employs 148 people, most of them part time.

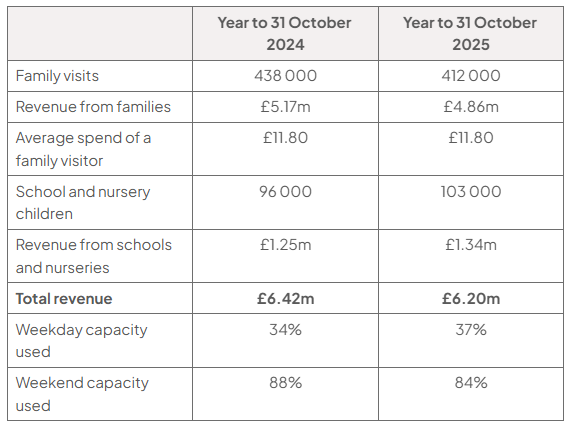
Almost all of the money comes from families. Last year 412 000 family visits brought in £4.86 million, an average of £11.80 a head once the café is counted. The rest, £1.34 million, came from schools and nurseries, who book weekday mornings a whole year ahead.

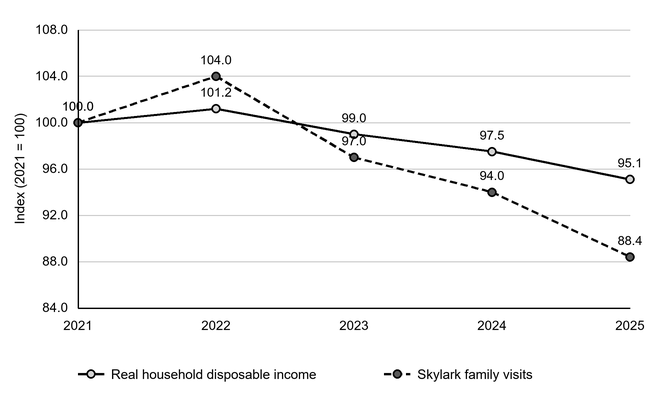
The two kinds of customer behave nothing like each other. A school booking is made in September for the following July and is almost never cancelled. A family visit is decided on a Saturday morning and is the first thing to go when money is tight. Appendix B shows what happened to family visits over five years as real household disposable income moved, and the two lines are hard to look at separately.

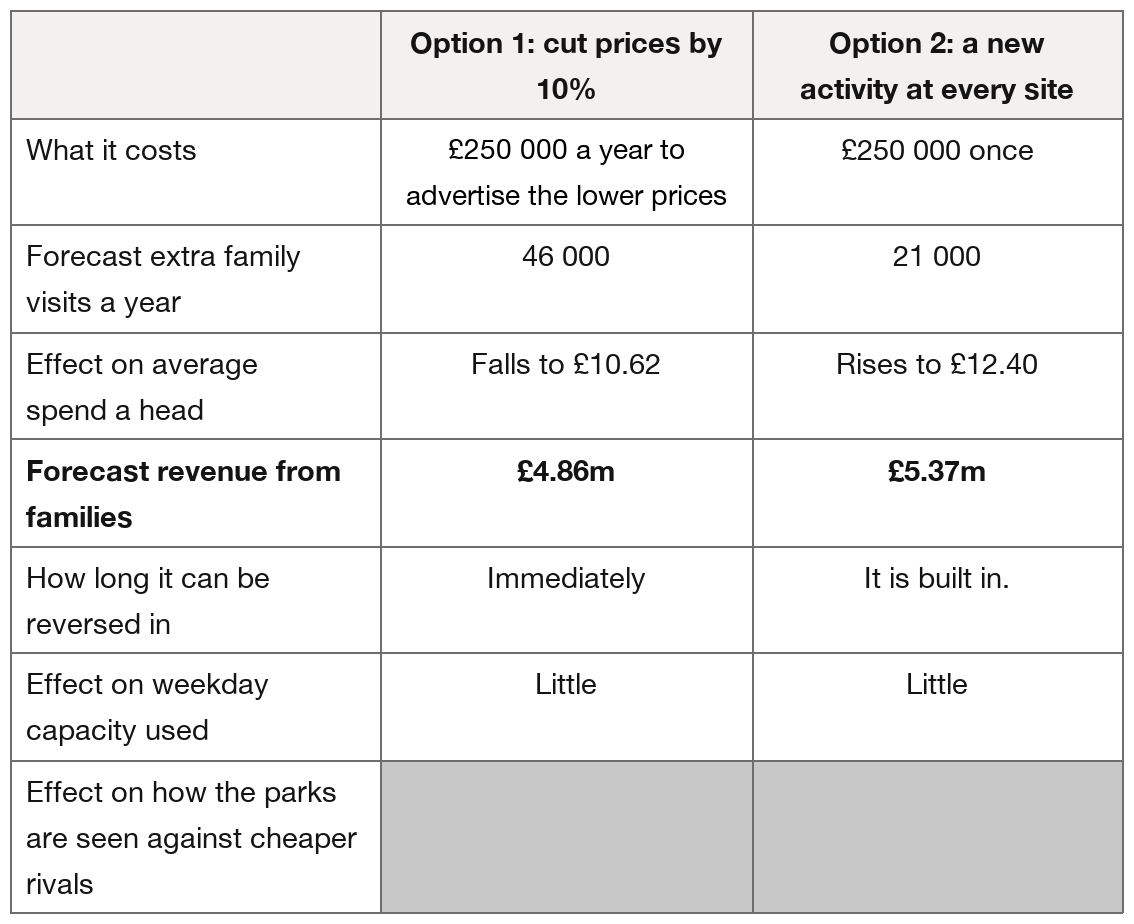
Ben Attah and Priya Shergill have £250 000 to spend across the six sites. They can lower prices, which they have never done, or they can put a new activity into every site and leave the price where it is. They are also arguing about something larger: whether a business that depends on families having spare money is one they should be trying to change.

Appendix A: Skylark Adventure Ltd, where the money comes from

Comparison table for years to 31 October 2024 and 2025: family visits 438 000/412 000; family revenue £5.17m/£4.86m; average spend £11.80 both; school children 96 000/103 000; school revenue £1.25m/£1.34m; total revenue £6.42m/£6.20m; weekday capacity 34%/37%, weekend 88%/84%.

Source: Analyst

Appendix B: Skylark Adventure Ltd family visits and household income

Line chart of indexed real household disposable income and Skylark family visits, 2021 to 2025 (2021=100): income 100, 101.2, 99, 97.5, 95.1; visits 100, 104, 97, 94, 88.4.

Source: Analyst

Appendix C: Data for two ways of spending £250 000

Comparison table of two ways of spending £250 000: option 1, cut prices by 10%, or option 2, a new activity at every site. What it costs: £250 000 a year to advertise the lower prices against £250 000 once. Forecast extra family visits a year: 46 000 against 21 000. Effect on average spend a head: falls to £10.62 against rises to £12.40. Forecast revenue from families: £4.86m against £5.37m. How long it can be reversed in: immediately against it is built in. Effect on weekday capacity used: little for both. Effect on how the parks are seen against cheaper rivals: not provided for either option.

Source: Analyst

Appendix C shows two ways in which Skylark Adventure Ltd could spend £250,000.

Evaluate whether Skylark Adventure Ltd should cut its prices by 10% or put a new activity into every site.

3
15 marks

Source A: Wrenfield Schoolwear Ltd

Wrenfield Schoolwear Ltd makes and sells school uniform from a unit in Nottingham: blazers, jumpers, skirts, trousers and PE kit, most of it carrying an embroidered school badge. Priya Wrenfield started it in 2009 after both her children came home in December with blazers that had already worn through at the elbow. The objective written into the company's own documents has never changed: to make uniform that lasts three years, and to keep a full set below £60. It is a private limited company and it employs 41 people.

It sells in two ways. Sixty-two schools have an exclusive supply contract with Wrenfield Schoolwear Ltd, which means a parent at one of those schools cannot buy the uniform anywhere else; the school receives a share of everything sold. That brought in £3 320 000 last year. The rest, £1 165 000, came from Wrenfield Schoolwear Ltd's own website, mostly from parents at schools with no exclusive supplier.

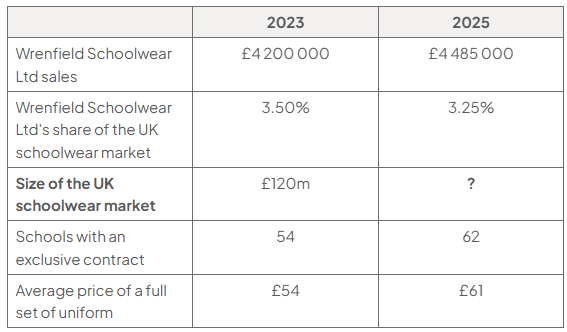
The marketing objective set two years ago was to grow sales by 5% by 2025. Sales rose from £4 200 000 to £4 485 000, which is 6.8%, and Priya Wrenfield has told the board the objective was met. Appendix A contains the figure she has not put in front of them.

A full set of uniform now costs a parent £61.

Wrenfield Schoolwear Ltd commissioned a survey last spring of 400 parents, 400 pupils and 96 school business managers, asking each of them to score four things out of ten. The results are in Appendix B. Priya Wrenfield has read them several times and has not yet decided what to do about them.

Appendix A: Wrenfield Schoolwear Ltd and the UK schoolwear market

Table comparing 2023 and 2025: sales £4.2m to £4.485m; market share 3.50% to 3.25%; UK market size £120m to ?; exclusive-contract schools 54 to 62; average full-set price £54 to £61.

Source: Analyst

Appendix C: Data for two routes to market

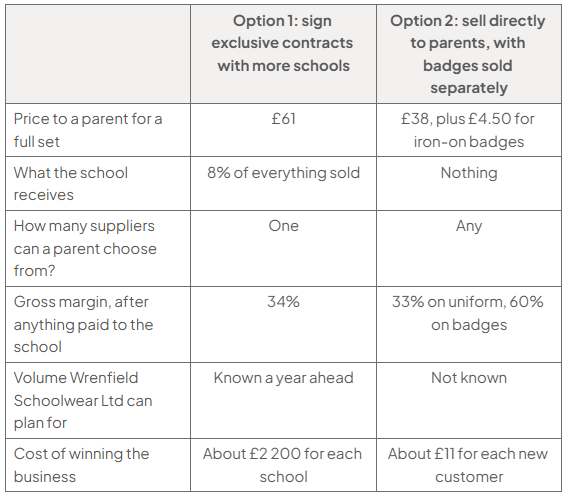
Table comparing exclusive school contracts with direct sales to parents: price £61 versus £38 plus £4.50 badges; school share 8% versus none; one supplier versus any; margins 34% versus 33%/60%; volume known versus unknown; acquisition £2,200 per school versus £11 per customer.

Source: Analyst

Appendix C sets out two routes to market for Wrenfield Schoolwear Ltd.

Evaluate both routes and recommend which one would be the better for Wrenfield Schoolwear Ltd.